Market News · October 28, 2026 · 市場新聞
Bank of Canada Raises Key Rate to 2.50% — What GTA Buyers & Sellers Should Do Now
加拿大央行加息至 2.50%:大多伦多买家与卖家现在该怎么做
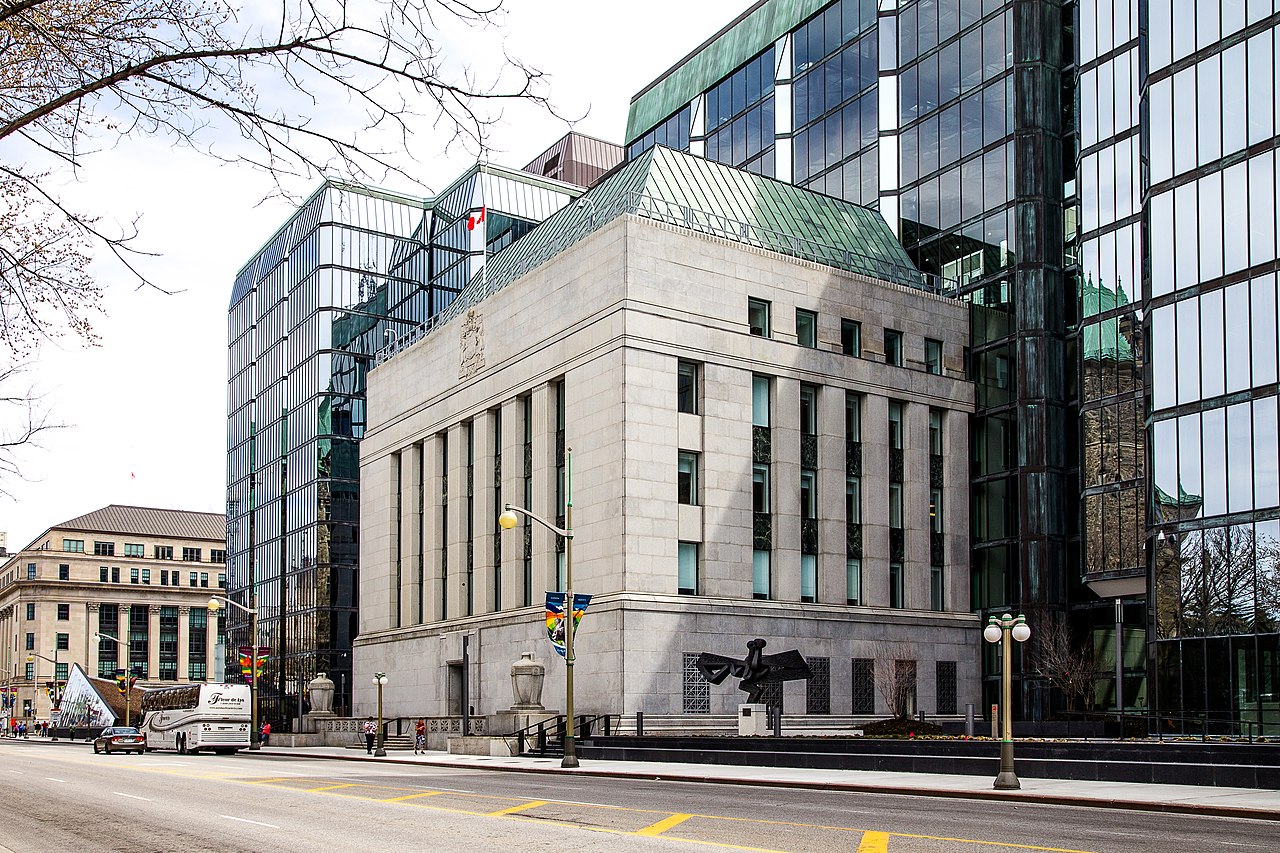
Bank of Canada head office, Ottawa. Photo from the web. 加拿大央行渥太华总部(网络图片)。
On Wednesday, October 28, 2026, the Bank of Canada raised its target for the overnight rate by 25 basis points to 2.50% — the first interest rate increase since July 2023, and the Bank's first policy move in a year. The Bank Rate is now 2.75% and the deposit rate 2.45%.
2026 年 10 月 28 日(周三),加拿大央行将隔夜目标利率上调 25 个基点至 2.50%,这是自 2023 年 7 月以来的首次加息,也是央行一年来的首次政策动作。目前银行利率为 2.75%,存款利率为 2.45%。
Key facts at a glance · 要点一览
- Rate: 2.25% → 2.50% (+25 basis points). Bank Rate 2.75%, deposit rate 2.45%.
- Why: Inflation has stayed around 3% since April, driven by persistently higher energy prices from the ongoing war in the Middle East. The Bank wants to stop elevated energy costs from spilling into broader inflation.
- Inflation: 3.2% in September, above the Bank's 1–3% target range; expected to reach about 3.5% by year-end, stay near 3% through most of 2027, and return close to 2% by mid-2028. Excluding gasoline, inflation was 2.2% in September.
- Growth: The economy is proving resilient — 1.0% growth expected in 2026, 2% in both 2027 and 2028 — but new U.S. tariffs are expected to slow activity in the fourth quarter, and housing is expected to remain relatively weak.
- What's next: Governor Tiff Macklem said "there could be a need to increase the policy rate further, but given uncertainties, we will proceed carefully." The next scheduled announcement is December 9, 2026.
- 中文要点:加息 25 个基点至 2.50%,为 2023 年 7 月以来首次;9 月通胀 3.2%,高于 1–3% 目标区间,预计年底升至约 3.5%,2027 年多数时间维持在 3% 附近,2028 年年中回落至 2%;行长 Macklem 表示未来可能需要进一步加息,但会谨慎行事;下次议息日为 2026 年 12 月 9 日。
What it means for your mortgage 对房贷意味着什么
Lenders are expected to raise their prime rates following the decision. That means higher payments for adjustable-rate mortgage borrowers, higher interest costs for fixed-payment variable mortgages, and higher carrying costs on HELOCs. Fixed mortgage rates, which follow bond yields rather than the policy rate, had already moved higher as sovereign bond yields rose.
各大银行预计将跟随上调最优惠利率(prime rate)。这意味着浮动利率房贷借款人的月供将上升,固定月供浮动房贷的利息成本增加,房屋净值信用额度(HELOC)的持有成本也会上升。而固定利率房贷跟随债券收益率定价,在国债收益率走高后已经先行上调。
As a rough guide, a 0.25% rate increase adds about $14 per month for every $100,000 borrowed on a 25-year amortization — about $70 a month on a $500,000 mortgage.
粗略测算:利率上升 0.25%,按 25 年摊还期计算,每 10 万加元贷款月供约增加 14 加元,50 万贷款约增加 70 加元/月。
Advice for buyers 给买家的建议
- 1
Re-run your numbers before you offer. Get your pre-approval refreshed at today's rates and stress-test your payment, not just your purchase price. A home you could comfortably carry at 2.25% needs a second look at 2.50% — and possibly higher.
出价前先重算月供。请银行按最新利率刷新预批,并按压力测试利率测算月供,而不只是看房价。2.25% 时轻松负担的房子,到了 2.50%(甚至更高)需要重新评估。 - 2
Don't panic-switch fixed vs. variable. Fixed rates already reflect higher bond yields, and the Bank says it will proceed carefully. Talk to a mortgage professional about your time horizon and risk tolerance before locking in or breaking a term.
不要恐慌切换固定/浮动利率。固定利率已反映走高的债券收益率,而央行表示会谨慎行事。结合持有周期和风险承受能力,先咨询房贷专业人士再做决定。 - 3
A cooling market is a negotiating window. As payments rise, some buyers pause — which means less competition for buyers who are prepared. Conditions for financing and inspection are your protection; use them.
市场降温是谈判窗口。月供上升会让部分买家观望,准备充分的买家反而竞争更小。贷款条件和验房条件是你的保护,一定要用好。 - 4
Buy the payment you can hold, not the bottom you can time. The Bank expects housing to remain relatively weak. Focus on the right home, the right location, and a payment you can carry for years — not on guessing the next announcement.
买你能长期负担的月供,而不是猜测市场底部。央行预计楼市仍将相对疲软,选对房子、选对地段、选一个多年都负担得起的月供,比猜下次议息结果更重要。 - 5
Move fast on well-priced homes. Rate hikes don't stop good homes from selling — they make buyers choosier. When a fairly priced home in a strong neighbourhood appears, hesitation costs more than the rate increase.
定价合理的好房要果断出手。加息不会让好房子卖不出去,只会让买家更挑剔。好地段定价公道的房子出现时,犹豫的代价比加息本身更大。
Advice for sellers 给卖家的建议
- 1
Price to today's market, not last spring's peak. Buyers now do the payment math first. An aspirational list price in a higher-rate market buys you days on market, not dollars.
按今天的市场定价,而不是去年春天的峰值。买家现在先算月供再出价,高利率市场里过高的挂牌价换来的只是更长的上市天数,而不是更高的成交价。 - 2
Presentation and exposure matter more than ever. When buyers are payment-sensitive, the homes that show beautifully, photograph beautifully, and reach the widest audience are the ones that still draw offers.
展示和曝光比以往更重要。买家对月供敏感时,展示出色、照片出色、触达面最广的房子,才是能拿到 offer 的房子。 - 3
Consider incentives before a price cut. A mortgage rate buydown or closing-cost credit can lower the buyer's monthly payment more visibly than an equivalent price reduction — and sometimes costs you less.
降价之前先考虑激励措施。利率买断(rate buydown)或成交费用补贴,能更直观地降低买家的月供,有时比同等降价花的钱更少。 - 4
Expect more conditions and longer timelines. Financing and inspection conditions are back. A clean, pre-inspected, well-documented home stands out immediately in this environment.
做好条件更多、周期更长的准备。贷款和验房条件又回来了,提前验房、文件齐全的房子在这种环境下立刻脱颖而出。 - 5
Proof: well-priced homes still sell fast. Days before this announcement, our Richmond Hill listing sold firm in 13 days, over asking — in this same market. The right price plus the right presentation still wins.
实例证明:定价合理的房子依然卖得快。就在本次加息公告前几天,我们列治文山的房源 13 天 firm 成交且高于要价——就是在同一个市场里。价格对了、展示对了,依然能赢。
Sources: Bank of Canada policy statement, October 28, 2026; Reuters; Canadian Mortgage Trends. Figures summarized for readers; see the Bank's full statement for details.
This article is general market information, not financial or mortgage advice. Mortgage terms vary by lender and borrower — speak with a licensed mortgage professional about your situation. 本文为一般市场信息,不构成金融或房贷建议,具体条款因银行和个人情况而异,请咨询持牌房贷专业人士。
Talk to Jason about your next move · 和 Jason 聊聊你的下一步
Buying or selling in a higher-rate market? Let's run your numbers and build a plan.
Call 416-877-6268 Email JasonFeatured listings · 精选房源
Currently on the market from Jason Gao's portfolio. Click a card for full details.